Starlink markets itself around a simple promise: unlimited satellite internet, anywhere. That promise holds up reasonably well in the US, Canada, and most of Western Europe. But according to Starlink’s own support documentation, a meaningful number of countries — many in Africa, Latin America, and Asia, along with a handful of European markets — currently have access only to Starlink’s Roam service, a plan tier with genuine, hard data caps rather than the deprioritization-based “unlimited” model residential customers elsewhere are used to.
What “Unlimited” Actually Means in the US and Europe
For residential customers in Starlink’s most mature markets, “unlimited” is a reasonably accurate description, even if it comes with an asterisk. Standard Residential plans don’t cut off service or charge overage fees once a customer crosses a certain data threshold. Instead, Starlink reserves the right to deprioritize heavy users during network congestion, meaning speeds can dip during peak hours if a customer’s usage consistently exceeds typical residential patterns. It’s a soft, usage-based system rather than a hard cutoff — annoying at worst, but not the kind of fixed limit that stops service outright.
The Markets Where Roam Is the Only Option Available
That’s not the experience available everywhere, though. According to Starlink’s own Roam support documentation, a specific list of countries currently have access only to Roam service plans, with no standard Residential option offered at all. That list includes Bangladesh, Botswana, Brunei, Cape Verde, Costa Rica, the Democratic Republic of the Congo, the Gambia, Kenya, Liberia, Malawi, the Maldives, Mozambique, and Nigeria — and, notably, three European Union members: Austria, Hungary, and Croatia. For customers in these markets, Roam isn’t a mobile add-on to a home internet plan; it’s the only Starlink service available to them at all.
How Roam’s Actual Hard Data Cap Works
Unlike Residential’s soft deprioritization model, Roam plans come with genuine, quantified data caps — typically 100GB or 300GB per billing cycle, depending on the specific plan purchased. Once a customer exceeds that allowance, their connection doesn’t get slower during busy periods the way a Residential user’s might; it switches to a low-speed unlimited mode instead, sufficient for email, calls, and text messaging but not much else. Streaming video, large downloads, and video calls become largely impractical once a Roam customer hits that ceiling, a stark contrast to how deprioritization works for Residential customers in more established markets.
Kenya’s Budget Tier: A Real, Hard-Capped Plan
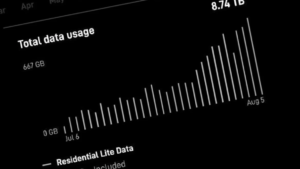
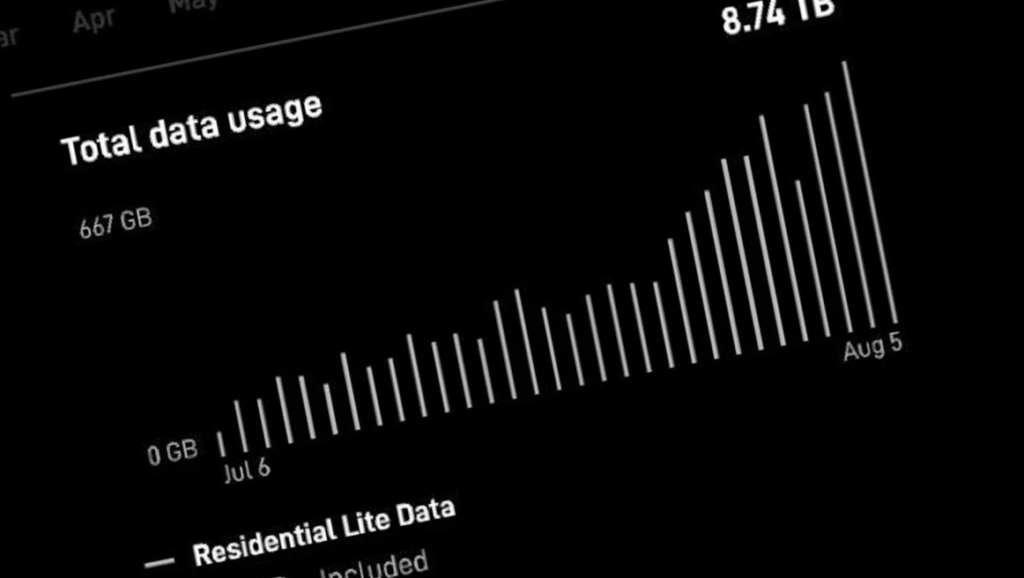
Kenya illustrates this regional gap particularly clearly. Alongside its Residential Unlimited plan, Starlink offers a Residential Lite option in Kenya priced at roughly KES 1,300 (around $10) per month, explicitly capped at 50GB of data. It’s a genuinely useful budget entry point for customers who can’t afford the full unlimited tier, but it’s also a real, hard data limit that simply doesn’t exist as an option for equivalent budget-conscious customers in the US or most of Europe, where the cheapest available plans still come with unlimited standard data.
Nigeria: Unlimited on Paper, but Access Isn’t Guaranteed
Nigeria’s situation adds a different wrinkle. The standard Residential plan there is technically unlimited, currently priced around ₦57,000 (about $39) per month with a 1TB fair use allowance before any deprioritization risk. The bigger issue in Nigeria isn’t the data policy itself — it’s availability. In high-demand areas of Lagos and Abuja, including Victoria Island, Ikoyi, and Lekki, Starlink has paused new Residential sign-ups entirely due to network congestion, pushing prospective customers toward a considerably more expensive Business Priority plan at roughly ₦159,000 (about $110) per month instead. For many Nigerian customers, the choice isn’t between capped and uncapped data — it’s between a much higher price tier or a waitlist with no confirmed timeline.
Why These Countries Don’t Get Full Residential Access Yet
Starlink’s rollout has consistently prioritized regulatory approval and satellite capacity in wealthier, higher-density markets first, with expansion into other regions following as licensing agreements are finalized and network capacity catches up with local demand. Countries limited to Roam-only access are, in effect, still waiting for Starlink to formally launch full residential service within their borders, even in cases — like Austria, Hungary, and Croatia — where the country’s broader economic profile doesn’t obviously explain the gap. Regulatory approval timelines, spectrum licensing, and local telecom rules likely play a bigger role in these specific holdouts than affordability or infrastructure limitations alone.
The Bigger Pattern: Coverage vs. Capability
Zooming out, the pattern here isn’t unique to Starlink — it mirrors how satellite and telecom rollouts have historically worked, with wealthier and higher-priority markets receiving full-featured service well before smaller or less commercially prioritized ones. What makes it notable in Starlink’s case is the gap between marketing and reality: the company’s global “unlimited internet, everywhere” positioning doesn’t fully account for the meaningfully different service tiers customers actually receive depending on which country they live in, something that’s easy to miss unless you’re specifically comparing plan pages market by market.
What This Means for Starlink’s Global Users
For prospective customers outside Starlink’s most mature markets, the practical takeaway is to check plan availability and specific data terms for their exact country before assuming the “unlimited” branding applies uniformly. Customers in Roam-only markets should expect real, enforced data ceilings rather than the softer deprioritization model US and European Residential customers experience, and pricing structures — as Nigeria and Kenya both demonstrate — can vary significantly even between neighboring markets. As Starlink continues expanding its regulatory footprint and satellite capacity globally, more of these Roam-only markets will likely gain full Residential access over time, but for now, “unlimited” remains a promise with real geographic limits.